AI in Credit Risk Management: A Guide for Enterprise Finance
Last Updated: 11 November, 2026
•
Editorial Team HighRadius
2026 Automation Benchmark Report
HighRadius 2026 Automation Benchmark Report For The Office Of The CFO
Understand if your performance is on par with top 10% of the organizations. Identify gaps, best practices and know how you can drive value through Agentic AI-Driven Automation.
AI helps identify emerging credit risks through real-time data and predictive analytics.
Automation speeds up credit assessments and improves decision-making.
Continuous risk monitoring helps finance teams manage credit exposure and prevent potential defaults.
AI in credit risk management refers to the use of machine learning, real-time data, and automation to assess customer creditworthiness, predict default risk, and improve credit decisions. Unlike traditional models that rely on static financial data, AI-powered credit risk management enables continuous risk monitoring and more accurate decision-making across the credit lifecycle.
80–90% of Credit Evaluations Don’t Need Manual Review.
Automate routine approvals, focus analysts on high-risk accounts, and improve portfolio visibility with continuous AI-driven risk monitoring.
AI-powered credit decisioning platform leverages the power of artificial intelligence and machine learning algorithms to analyze vast amounts of data, identify patterns, and make accurate predictions about credit risk. By automating credit risk assessment, an AI system built on a trained credit risk model can provide large enterprises with faster, more accurate, and more reliable credit risk assessments than traditional methods.
In addition, having a best credit scoring software and credit application for midmarket businesses and large enterprises helps manage credit risk effectively and efficiently. It offers a range of benefits, including improved accuracy, faster decision-making, reduced risk, and cost savings.
Not All AI Solutions Deliver Results. Most Just Add Complexity.
AI automation improves accuracy, detects risk patterns, and enables proactive credit and collections strategies at scale.
Artificial intelligence in credit risk is shifting how businesses evaluate, monitor, and control customer risk. Instead of relying on static data and periodic reviews, AI for credit risk assessment enables continuous, data-driven decision-making across the credit lifecycle.
Key ways AI in credit risk management is transforming operations include:
Real-time credit risk analysis AI credit risk evaluates customer behavior continuously using transactional and behavioral data, eliminating reliance on outdated financial snapshots.
Improved prediction accuracy Machine learning in credit risk management helps models identify complex risk patterns that traditional scoring methods often miss, leading to better default prediction.
Automated credit decisioning AI credit risk applies predefined policies and credit scoring models instantly, enabling faster, consistent credit approvals without manual intervention.
Dynamic risk monitoring Credit risk AI scores update in real time as customer behavior changes, allowing teams to proactively manage exposure and take timely action.
The Traditional Approach to Manage Credit Risk
Traditional methods of credit risk management involve a variety of manual processes, such as gathering information on potential borrowers, assessing their creditworthiness, and monitoring their credit performance over time. These processes rely heavily on human judgment and are often prone to errors, inconsistencies, and biases. These limitations affect risk management in financial institutions as much as enterprise finance teams, where manual reviews struggle to keep pace with growing portfolios.
That’s why, large enterprises now leverage AI-driven solutions for credit risk management. They use advanced, autonomous AI agents to accelerate credit reviews, ensure accurate credit decisioning and leverage AI-led credit scoring models to reduce past dues and credit risks.
AI vs Traditional Scorecard
Traditional credit scorecards typically assess creditworthiness using predefined criteria and periodic data updates. In contrast, AI-driven credit assessments can analyze a broader range of inputs, including financial information, payment behavior, and external credit signals. By incorporating changing customer data into risk assessments, AI models provide a more current view of creditworthiness and help finance teams make faster, more informed credit decisions.
Feature
Traditional
AI-Based
Data
Historical
Real-time + external
Analysis
Manual
Automated
Decision Speed
Slow
Instant
Risk Monitoring
Periodic
Continuous
What If 40% of Blocked Orders Could Be Released Without Manual Intervention?
Discover how AI-powered credit decisions and intelligent workflows can accelerate order release, reduce manual intervention and maintain credit risk controls.
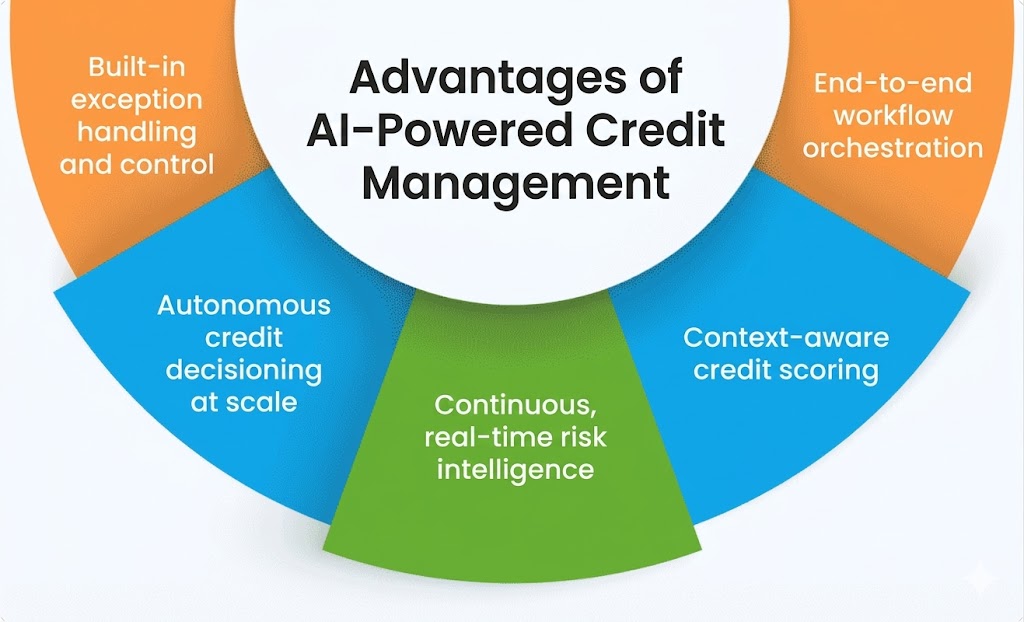
Agentic AI is redefining credit management by moving beyond static automation to autonomous, decision-driven workflows. Instead of just analyzing data, AI agents can continuously evaluate credit risk, trigger actions, and support decision-making across the credit lifecycle. Generative AI in credit risk complements these capabilities by helping summarize credit bureau reports and financial statements and draft credit review notes for analyst validation and approval.
Built-in exception handling and control
High-risk or complex cases are automatically routed for review, ensuring governance while maintaining speed and efficiency.
Autonomous credit decisioning at scale
AI agents independently assess creditworthiness, apply policies, and approve or escalate decisions in real time, eliminating manual bottlenecks.
Continuous, real-time risk intelligence
Instead of periodic reviews, agentic AI monitors customer behavior, payment patterns, and external signals continuously, enabling proactive trade credit risk management. AI-driven credit decisions also depend on reliable operational data. HighRadius integration with NetSuite connects configured customer, receivables, and payment information with credit assessment and monitoring workflows.
Context-aware credit scoring
AI dynamically adjusts risk scores and each customer’s risk profile based on evolving data inputs, ensuring more accurate and adaptive credit decisions across changing business conditions
AI-Powered Trade Credit Risk Assessment
In trade credit risk assessment, AI combines credit bureau data, customer payment history, and financial statements to evaluate the likelihood of late payments or default when businesses sell goods or services on credit terms. Based on changing risk indicators, AI-driven systems can recommend credit limit adjustments or automate updates within predefined credit policies, helping finance teams manage customer exposure proactively.
End-to-end workflow orchestration
From data collection to decisioning and monitoring, AI agents automate the entire credit process, ensuring consistency across teams, regions, and portfolios.
Challenges and Limitations of AI in Credit Risk Management
While AI can improve credit risk assessment and decision-making, its effectiveness depends on data quality, model transparency, and appropriate human oversight. Finance teams should consider the following challenges when implementing AI in credit management.
1. Explainability of AI Decisions
AI models may generate credit scores or risk recommendations without clearly explaining the factors behind them. This can make it difficult for credit analysts to justify credit limits, approval decisions, or blocked orders to internal stakeholders. Businesses should prioritize transparent scoring models that provide clear risk indicators and reason-coded recommendations.
2. Bias and Fairness in Scoring
AI models trained on biased or unrepresentative historical data may produce inconsistent risk assessments across customer segments. In B2B credit management, this can affect how customers are evaluated and credit limits are assigned. Using consistent scoring criteria, regularly reviewing model outputs, and maintaining auditable decision processes can help reduce potential bias.
3. Data Quality and Completeness
AI-driven credit assessments rely on accurate and up-to-date information. Incomplete credit applications, outdated bureau reports, and fragmented ERP data can affect the reliability of risk scores and recommendations. Finance teams should establish data validation processes and integrate reliable internal and external data sources to improve assessment accuracy.
4. Model Drift Over Time
Economic conditions, industry trends, and customer payment behavior can change, reducing the accuracy of models trained on historical data. A credit risk model that once performed reliably may no longer reflect current risk patterns. Regular model performance monitoring, validation, and retraining help ensure that risk assessments remain relevant as conditions evolve.
5. Human Oversight and Accountability
AI-generated recommendations should not replace analyst judgment, particularly when decisions involve high-value accounts, unusual risk patterns, or exceptions to established credit policies. Over-reliance on automated decisions can limit the consideration of important business context. A human-in-the-loop approach allows credit analysts to review exceptions, validate recommendations, and retain accountability for critical credit decisions.
Keeping AI Credit Decisions Transparent and Human-Controlled
AI can improve the speed and consistency of credit decisions, but finance teams need visibility into how those decisions are made. Transparent scoring, defined approval thresholds, and human oversight help organizations use AI while retaining control over credit policies and critical decisions.
Explainable, Reason-Coded Credit Scores
Credit scores should provide more than a risk rating. Analysts need visibility into the factors influencing each score, such as payment behavior, financial information, and external credit signals. Clear, reason-coded recommendations help teams understand why a customer was assigned a particular risk category or why an order was flagged for review.
Human-in-the-Loop Approval Thresholds
Not every credit decision requires the same level of scrutiny. AI can automate routine, low-risk assessments within predefined credit policies, while high-value transactions, elevated-risk accounts, and exceptions are routed to credit analysts. Analysts should retain the ability to review recommendations, override decisions, and apply business judgment where necessary.
Audit Trails and Governance
Credit decisions need to be traceable for internal reviews, compliance, and accountability. A well-governed AI system should maintain records of decision outcomes, approval histories, timestamps, and the data used in assessments. This allows finance teams and auditors to understand who approved a decision, when it was made, and what information informed it.
Ultimately, AI should strengthen the credit team’s ability to make informed decisions, not remove human accountability. The right balance of automation, transparency, and oversight allows businesses to scale credit operations while keeping critical decisions under control.
AI-Powered Credit Risk Management: How Does It Work?
1. Multi-Language Online Credit Applications for Onboarding Customers Globally
With a configurable online credit applicationttools, credit teams can onboard customers faster across the globe. Online Credit Applications can be configured and translated into any required language and based on customer segments. With pre-filled credit applications from the sales team, customers don’t need to spend a lot of time filling up the credit application.
2. Consolidated View of Credit Risk Globally
Credit teams can integrate across multiple ERPs, including Oracle, NetSuite, SAP, and Microsoft Dynamics, as well as across business units, to review credit risk exposure in a standardized global currency. Senior management can assess overall exposure across geographies to identify risk concentrations and develop strategies to reduce bad debt. They can also drill down into individual regions to review credit exposure in the respective local currency.
3. Automatically Extract Credit Data from 40+ Credit Agencies and Bureaus
Automatically extract credit reports, ratings, financials, and credit insurance information from 40+ global and local agencies such as D&B, Experian, CreditSafe, Equifax, and Serasa. With HighRadius Credit Cloud, credit teams can access a one-stop repository for all credit information required for global operations.
4. Automated Credit Scoring and Approval Workflows
Automated credit scoring is the swift evaluation of an individual’s or a business’s creditworthiness using advanced algorithms and predefined criteria. It assesses financial factors to generate a numerical score, streamlining decision-making for credit teams.
Integrated with collaborative e-workflows, these credit scoring models can be configured seamlessly across business units, geographies, or diverse customer segments.
5. Real-Time Credit Risk Monitoring
In the current economy, real-rime credit risk monitoring helps credit teams to monitor customer portfolios daily on a real-time basis. Credit analysts can receive real-time alerts related to bankruptcy, dips in credit scores, and changes in payment behavior to stay on top of risks and control overall bad debt. This way they can proactively manage the credit risk.
Templates
You’re Missing 25–40% Efficiency Gains With The Wrong Credit Risk Solution
Find out how automation scales credit operations while improving consistency and control.
Real-World Use Cases of AI in Credit Risk Management
AI in credit risk management is actively driving measurable outcomes for large enterprises by transforming how credit decisions are made, monitored, and scaled. The following examples highlight how organizations are using AI to move from manual, fragmented processes to automated, data-driven credit operations.
Mosaic’s success story
The Mosaic Company implemented an AI-driven credit risk management solution to streamline its credit approval process and improve decision efficiency across a large customer base.
By integrating data from credit bureaus, financial statements, and payment histories into a single system, the company enabled a unified and real-time view of customer risk. AI models then evaluated this data to generate consistent risk scores and drive decision-making.
The impact:
Improved consistency across credit evaluations
Reduced approval layers from nine to four, eliminating unnecessary manual intervention
Accelerated credit decision timelines without compromising risk controls
Case Studies
How this Fortune 500 company unlocked 50% credit decisions?
Here’s how AI-driven workflows helped Mosaic reduce credit delays and improve credit decision consistency.
Chevron Phillips Chemical, an American chemical manufacturer, also implemented an AI-powered credit risk management solution to automate their credit management processes.
The solution continuously analyzed customer data and identified early risk signals, enabling the credit team to act before issues escalated. Automated workflows ensured consistent credit reviews across accounts without manual intervention.
Key outcomes:
Automated credit reviews, improving speed and consistency
Best Practices for Adopting AI in Credit Risk Management
Adopting AI in credit risk management requires more than deploying a scoring model. Finance teams should establish reliable data foundations, validate AI-driven recommendations, and define clear decision controls before expanding automation across their credit operations.
1. Start with Shadow-Mode Testing
Run AI-based credit scoring alongside existing manual assessments without allowing the system to influence live decisions initially. Compare AI recommendations with analyst decisions and actual payment outcomes to evaluate accuracy, identify gaps, and build confidence before deployment.
2. Roll Out AI in Phases
Begin with a low-risk customer segment, a specific credit workflow, or one business unit rather than automating the entire portfolio at once. Evaluate performance at each stage and expand adoption based on measurable results and operational readiness.
3. Prepare Your Data and ERP Systems
Consolidate customer records, validate master data, and establish reliable connections with credit bureaus and internal financial systems. For businesses operating across multiple ERPs, consistent data integration is essential to provide AI models with a unified view of customer creditworthiness and exposure.
4. Define Human Approval Thresholds
Establish which routine, low-risk credit decisions AI can handle within predefined policies and which require analyst approval. Set escalation thresholds for high-value accounts, elevated-risk customers, and exceptions, and review them as model performance and team confidence evolve.
5. Monitor and Retrain AI Models Regularly
Track scoring accuracy, decision outcomes, false positives, and changes in customer payment behavior to identify model drift. Schedule periodic model reviews and retraining using relevant, updated data to ensure credit assessments remain aligned with changing business
How HighRadius Credit Management Solution Helps Accelerate Credit Decisioning
HighRadius Credit Management helps finance teams automate credit decisioning, standardize risk evaluation, and gain real-time visibility into customer exposure. By combining AI-driven scoring with automated workflows, it enables faster approvals, reduces manual effort, and improves control over credit risk.
With real-time credit risk analysis software and credit decisioning software, you can receive alerts for any changes in your customers’ credit profile and make data-driven credit decisions from unlimited credit reports. Our software integrates with your ERP system and can start monitoring your customers in just 30 days.
We offer configurable credit scoring software and approval workflows that can be customized based on geography, customer segments, business units, and other factors. You can fast-track credit approvals through complex corporate hierarchies, making the credit application process more efficient and streamlined.
Our highly configurable online credit application allows you to onboard customers across the globe with multi-language, customized credit applications embedded on your website. You can automatically capture financials, personal guarantees, and check bank references, reducing the need for manual data entry.
Our software also automatically extracts credit data from over 40+ global and local agencies, including credit ratings, financials, and credit insurance information. You can configure the auto-extracted data in your preferred currency, making it easier to analyze and interpret.
With AI-based blocked order management, you can auto-predict blocked orders based on the customers’ credit limit utilization and payment history. You can leverage AI-based release or partial payment recommendations for faster credit decisions, reducing the need for manual intervention.
Struggling With Incomplete Credit Applications?
Explore the #1 software that makes onboarding customer faster and easier
Accelerate payment recovery from delinquent customers and boost cash flow through automated collection workflows.
Cash App
Achieve same day cash application with automated remittance aggregation
Credit
Mitigate credit risk, reduce bad debt, and streamline customer onboarding with AI-powered insights.
Deductions
Reduce Revenue Leakage with AI Prediction models that identify valid and invalid deductions.
Online Credit Application
Onboard customers seamlessly with a configurable online credit application. Cut down on back-and-forth and collect all customer details in one go.
Frequently Asked Questions (FAQs)
1. What is the role of AI in credit risk management?
AI plays a pivotal role in credit risk management by employing advanced algorithms to swiftly analyze vast datasets. It enhances decision-making accuracy, identifies patterns, and assesses creditworthiness, ultimately providing a more comprehensive and efficient approach to managing credit risks.
2. What are the main benefits of using AI in credit risk management?
With AI-Powered Credit Management Software, credit teams can achieve 100% real-time credit risk monitoring to ensure lower bad debt by tracking changes in customer credit risk and payment behavior. AI can be leveraged to predict blocked orders based on past order volumes and payment patterns.
3. What is credit risk monitoring?
Credit risk monitoring involves continuous assessment and surveillance of borrowers’ credit profiles. It utilizes data analysis and key indicators to track changes in creditworthiness, helping lenders identify potential risks and make informed decisions to mitigate financial losses.
4. How can an organization choose credit risk tools and measure their results?
Evaluate tools based on credit scoring accuracy, ERP integration, workflow automation, risk monitoring, and scalability. Measure results through faster credit decisions, improved assessment accuracy, reduced bad debt, lower manual effort, and better visibility into customer exposure.
5. How can an organization implement AI for credit risk management effectively?
Start with reliable data and shadow-mode testing alongside existing credit assessments. Roll out AI in phases, define human approval thresholds, integrate ERP and bureau data, and regularly monitor model accuracy, decision outcomes, and model drift.
Resource Library
Resource Hub
Order to Cash
Order to Cash software data sheet
Disconnected workflows can leave teams chasing data, while automated O2C has delivered 20% lower past dues.
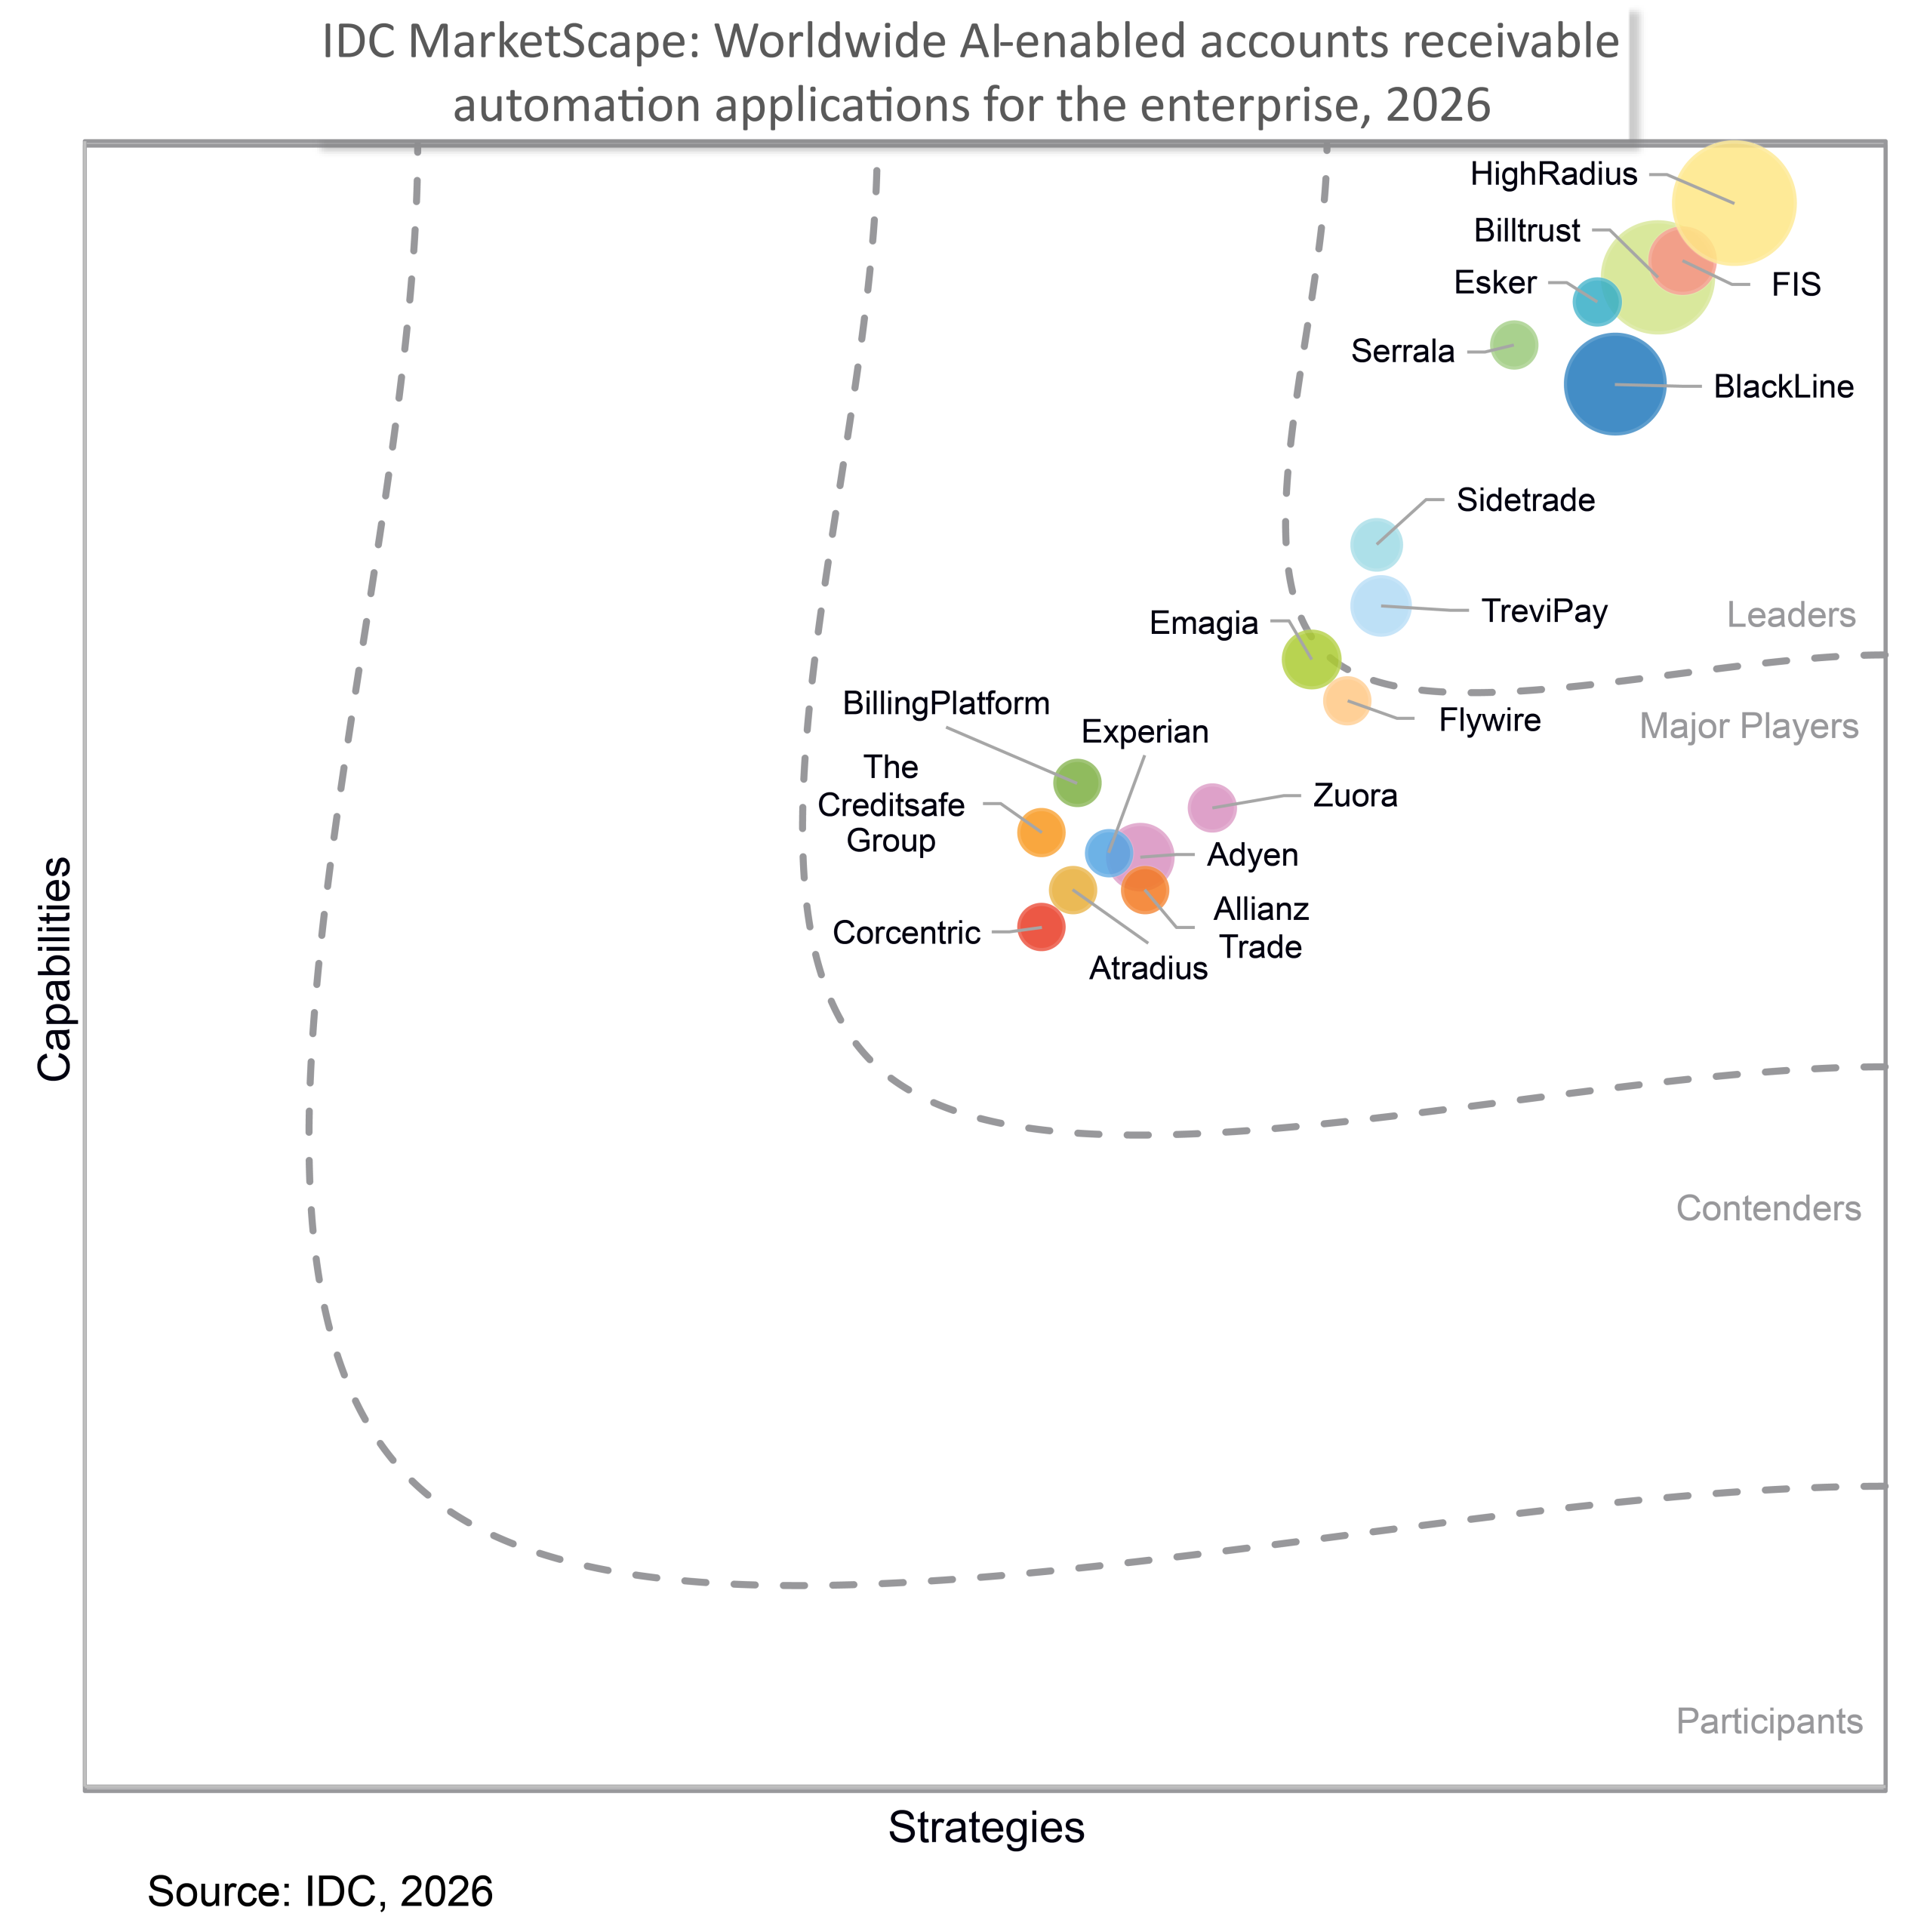
HighRadius recognized as a "Leader" in IDC Marketscape: Worldwide AI-enabled accounts receivable automation applications for the enterprise 2026 vendor assessment
Recognized as a Leader in 2026 Vendor Assessment for unifying credit, collections, cash application, deductions, e-invoicing, and payments on one AI platform to advance enterprise-wide invoice-to-cash transformation.
Forrester Recognizes HighRadius in The AR Invoice Automation Landscape Report, Q1 2023
Forrester acknowledges HighRadius’ significant contribution to the industry, particularly for large enterprises in North America and EMEA, reinforcing its position as the sole vendor that comprehensively meets the complex needs of this segment.